
The lending process involves multiple steps, from collecting loan applications and verifying borrower information to assessing creditworthiness, approving applications, and preparing loan documents. Managing these tasks manually can create delays, increase the risk of errors, and make it difficult for lenders to deliver a smooth borrower experience. Loan origination system software helps financial institutions simplify these activities by automating workflows, centralizing borrower data, and improving communication between lending teams.
As banks, credit unions, mortgage lenders, and other financial institutions adopt digital lending solutions, an efficient loan origination system (LOS) has become an important part of modern lending operations. By connecting different stages of the loan lifecycle, this software helps lenders process applications more efficiently while maintaining better visibility into application status, documentation, and approval decisions.
What Is Loan Origination System Software?
Loan origination system software is a digital platform that manages the process of creating, evaluating, and approving loans. It supports lenders from the initial application through underwriting, decision-making, and loan closing, depending on the system’s capabilities.
Traditional lending processes often rely on spreadsheets, emails, paper documents, and disconnected systems. These methods can make it difficult to track applications, identify missing information, and coordinate tasks between departments. An LOS brings many of these activities into a centralized workflow, allowing lending teams to access relevant information and manage applications more consistently.
Modern loan origination platforms may include application portals, document management, credit data integrations, automated underwriting support, compliance checks, reporting tools, and electronic signatures. The exact features depend on the provider, loan type, and lender’s operational requirements.
1. Automates Loan Application Processing
Loan application processing is one of the first areas where automation can make a significant difference. When applications are handled manually, employees may need to enter borrower details into multiple systems, review forms individually, and follow up repeatedly for missing information.
Loan origination system software can simplify this process by allowing borrowers to submit applications through online portals. The system can capture personal details, employment information, income, requested loan amounts, and other relevant data in a structured format.
Automated validation rules can identify incomplete fields, inconsistent information, or missing documents before an application moves to the next stage. This helps reduce unnecessary back-and-forth communication and allows loan officers to focus on applications that require attention.
For example, a mortgage lender receiving dozens of applications each day can use an LOS to organize submissions, identify incomplete applications, and route completed files to the appropriate team. This creates a more organized starting point for the lending process.
2. Centralizes Borrower Information and Documents
Lending decisions depend on accurate borrower information. Applications may require identification documents, income statements, bank records, tax documents, credit reports, and other supporting materials. When these records are spread across email inboxes, shared drives, and separate applications, retrieving the right information can become time-consuming.
A loan origination system creates a centralized location for borrower records and application-related documents. Authorized employees can review the information they need without repeatedly requesting files from other departments.
Document management features can also help lenders track which documents have been submitted, which remain outstanding, and whether additional verification is necessary. Some systems support automated document classification, data extraction, and notifications when information is missing or requires review.
Centralized records improve visibility throughout the application lifecycle. They can also support internal audits and recordkeeping when the system is configured according to the lender’s policies and applicable retention requirements.
3. Speeds Up Credit Assessment and Underwriting
Underwriting is a critical part of lending because it helps determine whether an applicant meets the lender’s eligibility and risk requirements. Traditional underwriting can involve reviewing multiple documents, calculating financial ratios, verifying information, and applying lending policies.
Loan origination system software can streamline this stage by consolidating relevant borrower data and applying configurable business rules. Depending on the integrations and capabilities available, the system may retrieve credit information, calculate debt-to-income ratios, check eligibility criteria, and flag applications that need further review.
Automated underwriting tools can help prioritize routine applications and identify cases requiring manual assessment. However, automation does not eliminate the need for appropriate human oversight, particularly when applications involve unusual circumstances or complex risk factors.
For example, if an applicant’s income documentation is incomplete or the reported financial information does not match the available records, the system can flag the discrepancy for a loan officer or underwriter. This makes it easier to identify potential issues before a final lending decision is made.
4. Improves Workflow Management and Task Assignment
A loan application often passes through several departments, including application processing, verification, underwriting, compliance, and closing. Without a defined workflow, applications may remain unattended while teams wait for updates or clarification.
Loan origination software helps lenders establish structured workflows that determine what happens at each stage. Applications can be routed to the appropriate employees based on loan type, eligibility criteria, workload, or internal policies.
Automated notifications and task reminders can alert employees when an application needs review, a document requires verification, or an approval is pending. Managers can also monitor application progress and identify bottlenecks that affect processing times.
These capabilities make responsibility clearer and reduce the likelihood of tasks being overlooked. They also help lending teams maintain a more consistent process across different branches, departments, or loan products.
5. Enhances Borrower Communication and Experience
Borrowers want clear information about their applications, including the documents they need to provide, the progress of their applications, and the next steps in the process. Limited communication can lead to repeated inquiries, uncertainty, and frustration.
A modern loan origination system can improve the borrower experience through online application portals, status updates, automated notifications, and secure document submission. Borrowers may be able to check their application progress, respond to information requests, and upload supporting files without visiting a branch or relying entirely on phone calls.
For lending teams, these tools can reduce routine administrative work and make it easier to communicate consistently with applicants.
A better digital experience is particularly useful for lenders managing applications across multiple locations or serving borrowers who prefer to complete financial transactions online. Nevertheless, the system should provide accessible alternatives for applicants who need additional assistance.
6. Supports Regulatory Compliance and Risk Controls
Financial institutions must follow applicable laws, regulations, and internal lending policies. Depending on the jurisdiction and loan type, these requirements may cover identity verification, consumer protection, fair lending, data privacy, documentation, and recordkeeping.
Loan origination system software can help support compliance by incorporating configurable validation rules, required approval steps, document checklists, and audit trails. These features can help lenders record important actions, identify missing information, and demonstrate how an application moved through the approval process.
Some platforms also integrate with identity verification services, fraud detection tools, and compliance screening systems. These integrations can reduce manual effort and help teams identify issues that require further investigation.
However, using loan origination software does not automatically guarantee regulatory compliance. Lenders remain responsible for selecting appropriate controls, maintaining accurate policies, reviewing system configurations, and ensuring that automated decisions are lawful, explainable, and properly monitored.
7. Integrates with Other Lending and Financial Systems
Lenders often use multiple technologies to manage customer relationships, verify financial information, assess credit risk, process payments, and maintain loan records. When these systems operate independently, employees may need to enter the same information more than once.
Loan origination system software can connect with other platforms through APIs, built-in integrations, or data exchange tools. Depending on the lender’s technology environment, these integrations may include:
- Credit bureaus: Retrieve credit information needed for application assessment.
- Customer relationship management systems: Share borrower information and support communication.
- Banking and financial data services: Help verify income, account information, or financial activity.
- Document and e-signature platforms: Support digital document workflows and signing.
- Loan servicing systems: Transfer approved loan information for ongoing account management.
- Reporting and analytics tools: Provide insights into application volumes, approval rates, and processing performance.
Effective integration reduces duplicate data entry and helps employees work with more consistent information. Before selecting a platform, lenders should evaluate integration availability, data security, implementation complexity, and compatibility with existing systems.
8. Provides Real-Time Reporting and Performance Insights
Understanding how loan applications move through the lending process is essential for improving operational performance. Without reliable reporting, managers may struggle to determine why applications are delayed, where workloads are increasing, or which stages require additional resources.
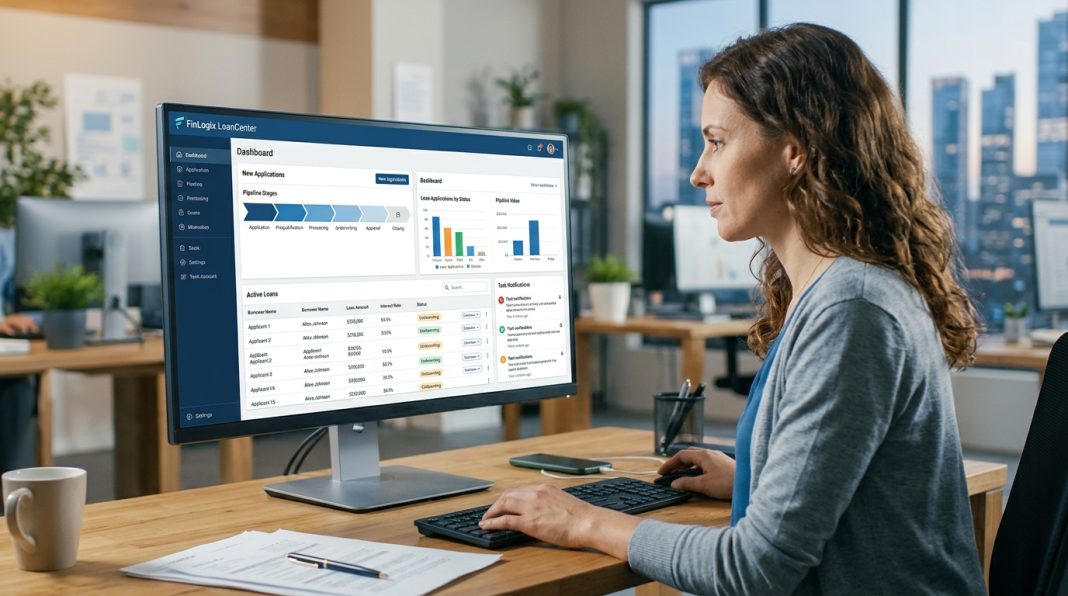
Many loan origination platforms provide dashboards and reports that show application volumes, processing stages, pending tasks, approval outcomes, and employee workloads.
Lenders can use these insights to monitor key performance indicators, such as:
- Average loan application processing time.
- Time spent in underwriting and verification.
- Application completion and withdrawal rates.
- Approval and rejection rates.
- Frequency of missing or incorrect documents.
- Bottlenecks between application stages.
By reviewing these metrics, management can identify opportunities to improve workflows and allocate resources more effectively. Reporting quality depends on accurate data, appropriate metric definitions, and consistent use of the system.
9. Reduces Administrative Work and Operational Expenses
Manual lending processes require employees to perform repetitive activities, including data entry, document organization, status updates, and routine follow-ups. These tasks consume time that could otherwise be spent on complex applications and borrower support.
Loan origination system software can reduce this administrative burden by automating repetitive tasks and standardizing processes. Centralized records can also reduce time spent searching for documents, while workflow automation can minimize delays caused by missed notifications or unclear responsibilities.
Over time, these improvements may help lenders process applications with greater efficiency and manage growing volumes without increasing administrative work at the same rate.
The actual financial benefit depends on factors such as implementation costs, licensing fees, integration requirements, employee training, and the amount of manual work eliminated. Lenders should evaluate total cost of ownership rather than assuming that automation will automatically reduce expenses.
Key Features to Look for in Loan Origination System Software
Choosing the right platform requires more than comparing software prices. Lenders should consider how well a solution supports their loan products, existing processes, security requirements, and long-term business goals.
| Feature | Why It Matters |
|---|---|
| Digital application management | Simplifies application submission and data collection. |
| Workflow automation | Routes tasks and applications to the appropriate teams. |
| Document management | Organizes borrower files and tracks missing information. |
| Underwriting support | Helps apply eligibility rules and assess risk. |
| Compliance controls | Supports required checks, approvals, and audit trails. |
| System integrations | Connects lending operations with external data sources and internal platforms. |
| Reporting and analytics | Helps managers monitor performance and identify bottlenecks. |
| Security and access controls | Helps protect sensitive borrower information. |
| Scalability | Supports changes in application volume and lending requirements. |
Lenders should also assess vendor support, customization options, implementation timelines, data migration, disaster recovery, and the availability of ongoing software updates. A platform that fits existing processes and can adapt to future requirements is often more valuable than one offering numerous features that the organization does not need.
How to Implement a Loan Origination System Successfully
Implementing loan origination software requires careful planning. The goal should be to improve the lending process, not simply move existing manual tasks into a digital platform.
Start by reviewing current workflows. Identify delays, duplicate data entry, repeated document requests, and approval bottlenecks. Establish measurable goals, such as reducing incomplete applications or shortening the time required to assign applications to underwriters.
Choose a system that matches your lending needs. Evaluate whether the platform supports your loan products, risk policies, borrower requirements, and regulatory environment. Confirm which features are included and which require third-party integrations.
Plan data migration and integration. Determine how existing borrower records will be transferred, validated, and protected. Test integrations to ensure information moves accurately between systems.
Train employees and communicate changes. Loan officers, underwriters, compliance teams, and administrators need to understand their responsibilities within the new workflows. Training should include exception handling and procedures for resolving system issues.
Test before full deployment. Run representative applications through the system, including incomplete submissions, unusual underwriting cases, and compliance-related scenarios. Resolve problems before expanding usage.
Monitor results and improve continuously. Compare performance against the original goals and collect feedback from employees and borrowers. Adjust workflow rules and system configurations as lending needs evolve.
Frequently Asked Questions
1. What is the main purpose of loan origination system software?
Its primary purpose is to manage and streamline the loan application process, from initial submission through assessment, underwriting, approval, and closing. Depending on the platform, it can automate tasks, organize documents, coordinate employees, and provide application tracking.
2. How does loan origination software speed up loan approvals?
It can reduce delays by automating data validation, organizing documents, routing applications to the appropriate teams, and supporting underwriting decisions. Approval speed still depends on borrower documentation, lender policies, risk complexity, and required verification procedures.
3. Who can benefit from loan origination system software?
Banks, mortgage lenders, credit unions, fintech companies, consumer finance providers, and commercial lenders can benefit from an LOS. The most suitable solution depends on the institution’s loan products, application volumes, and operational requirements.
4. Is loan origination software the same as loan servicing software?
No. Loan origination software focuses primarily on application processing, underwriting, and loan approval. Loan servicing software manages activities after a loan is issued, such as payment collection, account administration, and repayment tracking. Some financial technology platforms support both functions.
5. Is cloud-based loan origination software secure?
Cloud-based systems can provide security features such as encryption, role-based access controls, monitoring, backups, and secure integrations. However, security depends on the provider’s practices, system configuration, access management, and the lender’s own controls. Organizations should assess security documentation and contractual responsibilities before adoption.
6. Can loan origination systems integrate with existing banking software?
Yes, many platforms offer APIs and integrations with banking systems, credit bureaus, CRM tools, document services, and loan servicing applications. Compatibility varies by vendor, so lenders should confirm integration requirements before implementation.
Conclusion
Loan origination system software helps modern lenders manage applications more efficiently by connecting data collection, document management, underwriting, workflow automation, compliance controls, and reporting in a coordinated process. These capabilities can reduce repetitive administrative tasks, improve application visibility, and create a more consistent experience for borrowers and employees.
For financial institutions looking to modernize their lending operations, selecting the right LOS starts with understanding existing challenges, defining measurable objectives, and evaluating solutions against real business requirements. With appropriate implementation, training, security controls, and ongoing monitoring, loan origination software can become a valuable foundation for efficient and scalable lending operations.