You’ve bought the saw, lined up a skidder, and maybe even shaken hands on your first timber tract. Before a single tree hits the ground, though, one more piece needs to be in place: logging insurance. Without it, one accident on your first job could wipe out everything you’ve put into the business.
New owners often treat logging insurance as paperwork to handle later. That’s a risky approach. Landowners and mills usually ask for proof of coverage before they sign a contract, and the risks of timber work start on day one, not after your first profitable season.
This guide explains the logging insurance policies a new business should have in place and how to set up coverage that grows with you.
Why logging insurance comes before the first contract
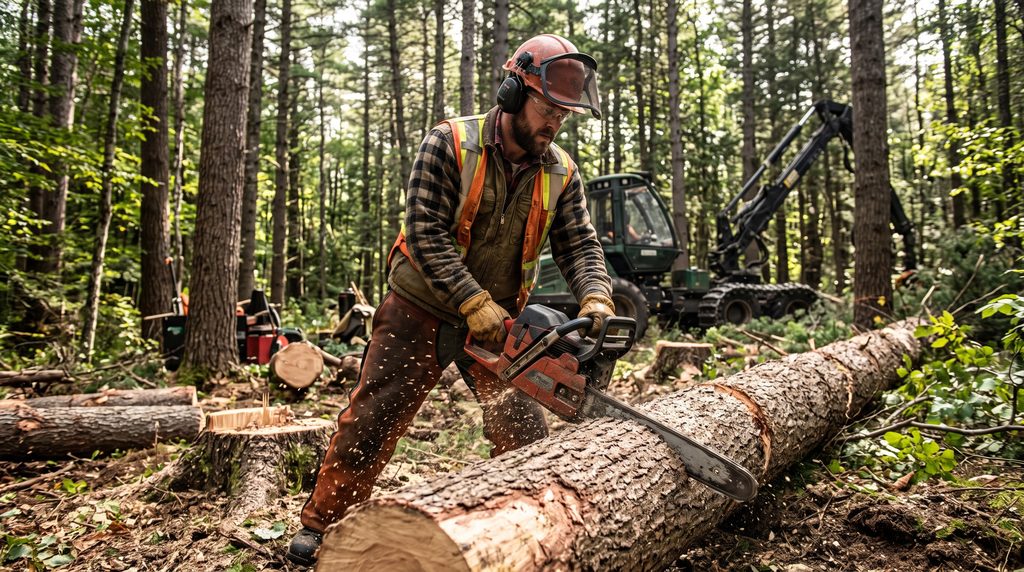
Logging is one of the most hazardous lines of work in the country. Crews deal with falling timber, moving machinery, steep ground, and heavy loads, often far from help. Logging insurance exists because those risks don’t wait until you’re established.
Many buyers won’t let you start without it. Landowners, timber buyers, mills, and general contractors commonly require a certificate of insurance showing your logging insurance limits before you set foot on the property. If you can’t produce one, the job goes to someone who can.
There’s also a legal side. Most states require businesses with employees to carry workers’ compensation, and any vehicle you drive on public roads needs auto coverage. Getting your logging insurance in order early keeps you compliant from the start.
The core logging insurance policies every new operation needs
A good logging insurance program is built from several policies. Each one handles a different kind of risk, and together they cover the main ways a timber business can lose money.
General liability insurance
General liability is the foundation of logging insurance. It covers claims from third parties who say your work injured them or damaged their property. Picture a tree that lands on a neighbor’s fence or a hiker hurt near your landing. General liability helps pay legal fees, medical costs, and settlements.
This is usually the first policy a landowner asks about. Make sure the general liability portion of your logging insurance carries limits that meet the contracts you plan to bid.
Workers’ compensation insurance
If you hire even one employee, workers’ compensation belongs in your logging insurance plan. It pays medical bills, rehabilitation costs, and a portion of lost wages when a worker is hurt or becomes ill on the job. It also protects your business from most injury lawsuits brought by employees.
Workers’ comp is often the largest single cost in logging insurance because of the risks involved. Accurate payroll reporting and correct job classifications keep that cost fair.
Commercial auto insurance
Personal auto policies don’t cover business use, and log trucks are a different animal entirely. Commercial auto coverage within your logging insurance protects trucks, trailers, and crew vehicles against accidents, theft, and damage. It also covers liability if your vehicle injures someone or damages their property on the road.
If you haul your own timber, tell your agent. Log hauling carries its own risks, and your logging insurance should reflect them.
Inland marine insurance
Your equipment rarely stays in one place. Saws, skidders, loaders, and trailers move from tract to tract and sit in the woods overnight. Standard property policies usually cover items at a fixed address, which leaves mobile equipment exposed. That’s one of the most common blind spots in a new logging insurance program.
Inland marine coverage fills that gap in your logging insurance. It protects machinery and tools while in transit, at job sites, and in temporary storage against theft, fire, vandalism, and accidents.
Equipment breakdown insurance
A skidder with a blown hydraulic system can stop a job cold. Equipment breakdown coverage pays to repair or replace machinery that fails from mechanical or electrical causes. Inland marine generally doesn’t cover a breakdown, so this piece of logging insurance keeps your crew working when a machine quits.
Property insurance
If you own or rent a shop, office, or storage yard, property coverage belongs in your logging insurance. It protects buildings and stored inventory from fire, storms, theft, and vandalism.
Commercial umbrella insurance
A serious accident can produce a claim larger than your underlying limits. Commercial umbrella coverage adds an extra layer of logging insurance on top of your general liability, auto, and employer’s liability limits. Many new owners skip it. Larger contracts often require it, though, and it can keep a single lawsuit from closing your doors.
Who needs logging insurance
Logging insurance isn’t only for large harvesting companies. Any business that cuts, moves, or processes timber faces the same basic risks. You likely need logging insurance if you run one of these operations:
- An owner-operator who cuts and skids timber alone
- A small crew handling contract cutting for landowners
- A timber harvesting company with multiple crews
- A log hauling business moving timber to mills
- A land clearing service preparing sites for construction or farming
Even a one-person operation needs liability and auto coverage at a minimum. As soon as you add workers or equipment, your logging insurance needs grow.
What to have ready when you apply for logging insurance
Underwriters need detailed information to price a new logging business. Pulling it together before you call speeds up the process and leads to a more accurate quote. When you request logging insurance, plan to provide:
- A description of the services you’ll offer, such as felling, skidding, loading, or hauling
- Estimated annual revenue and payroll
- The number of employees and their job duties
- A list of equipment with year, make, model, and value
- Vehicle details and driver information, including license and driving records
- Your prior experience in the timber industry
- Any written safety procedures or training you’ve completed
Your personal background matters for a new business. Years spent working on another crew can help you qualify for better logging insurance terms, even if your company is brand new.
What shapes the cost of logging insurance for a new business
There’s no flat rate for logging insurance. Your premium depends on the work you do, the size of your payroll, the value of your equipment, and where you operate. A crew that fells timber on steep ground will pay more than a land clearing service working flat pasture.
Your choices also play a part. Higher deductibles lower your logging insurance premium but mean more out of pocket after a claim. Higher liability limits cost more but open the door to larger contracts. A good agent will walk you through these trade-offs instead of quoting the cheapest policy on the market.
Budget for logging insurance as a regular operating cost, the same way you budget for fuel and saw chain. Owners who plan for it from the start are far less likely to let coverage lapse during a slow month.
Common logging insurance mistakes new owners make
Some mistakes cost money right away. Others don’t show up until a claim gets denied. Watch for these problems when setting up logging insurance:
- Underinsuring equipment to lower the premium, then coming up short after a total loss
- Misclassifying employees as independent contractors to avoid workers’ comp
- Hiring subcontractors without checking that they carry their own logging insurance
- Choosing liability limits too low to qualify for larger contracts
- Forgetting to update coverage after buying new machines or adding a truck
Each of these can leave a gap that shows up at the worst time. A periodic review of your logging insurance with your agent catches most of them before they hurt you.
How to keep logging insurance affordable in your first years
New businesses don’t have a claims history, which can make early logging insurance quotes higher. You can still take steps that improve your standing over time.
Start with safety. Train every worker on chainsaw handling, felling methods, and equipment operation. Require protective gear on every job. Write your procedures down and keep training records. Underwriters look closely at these practices when they renew logging insurance.
Keep good records too. Accurate payroll, revenue, and equipment lists prevent surprise audit bills and make each renewal smoother. Report claims quickly and cooperate with the adjuster. Small claims handled well do less damage to your logging insurance history than claims that drag on.
Finally, review your coverage every year. Your logging insurance should change as your business grows. A policy built for a two-person crew won’t fit a company running three crews and a log truck.
Start your logging business protected with Burton & Company
The first cut is a big step, and the right logging insurance lets you take it with confidence. Burton & Company works with logging contractors, timber harvesting companies, log haulers, and land clearing services to build coverage that matches their risks. Our agents help new owners pick the right mix of policies, so your logging insurance is ready before your first contract.
Visit the Burton & Company website to request a quote online to talk with an agent about logging insurance for your new business.